All Categories
Featured


Evaluating PPO and HMO Insurance
Table of Contents
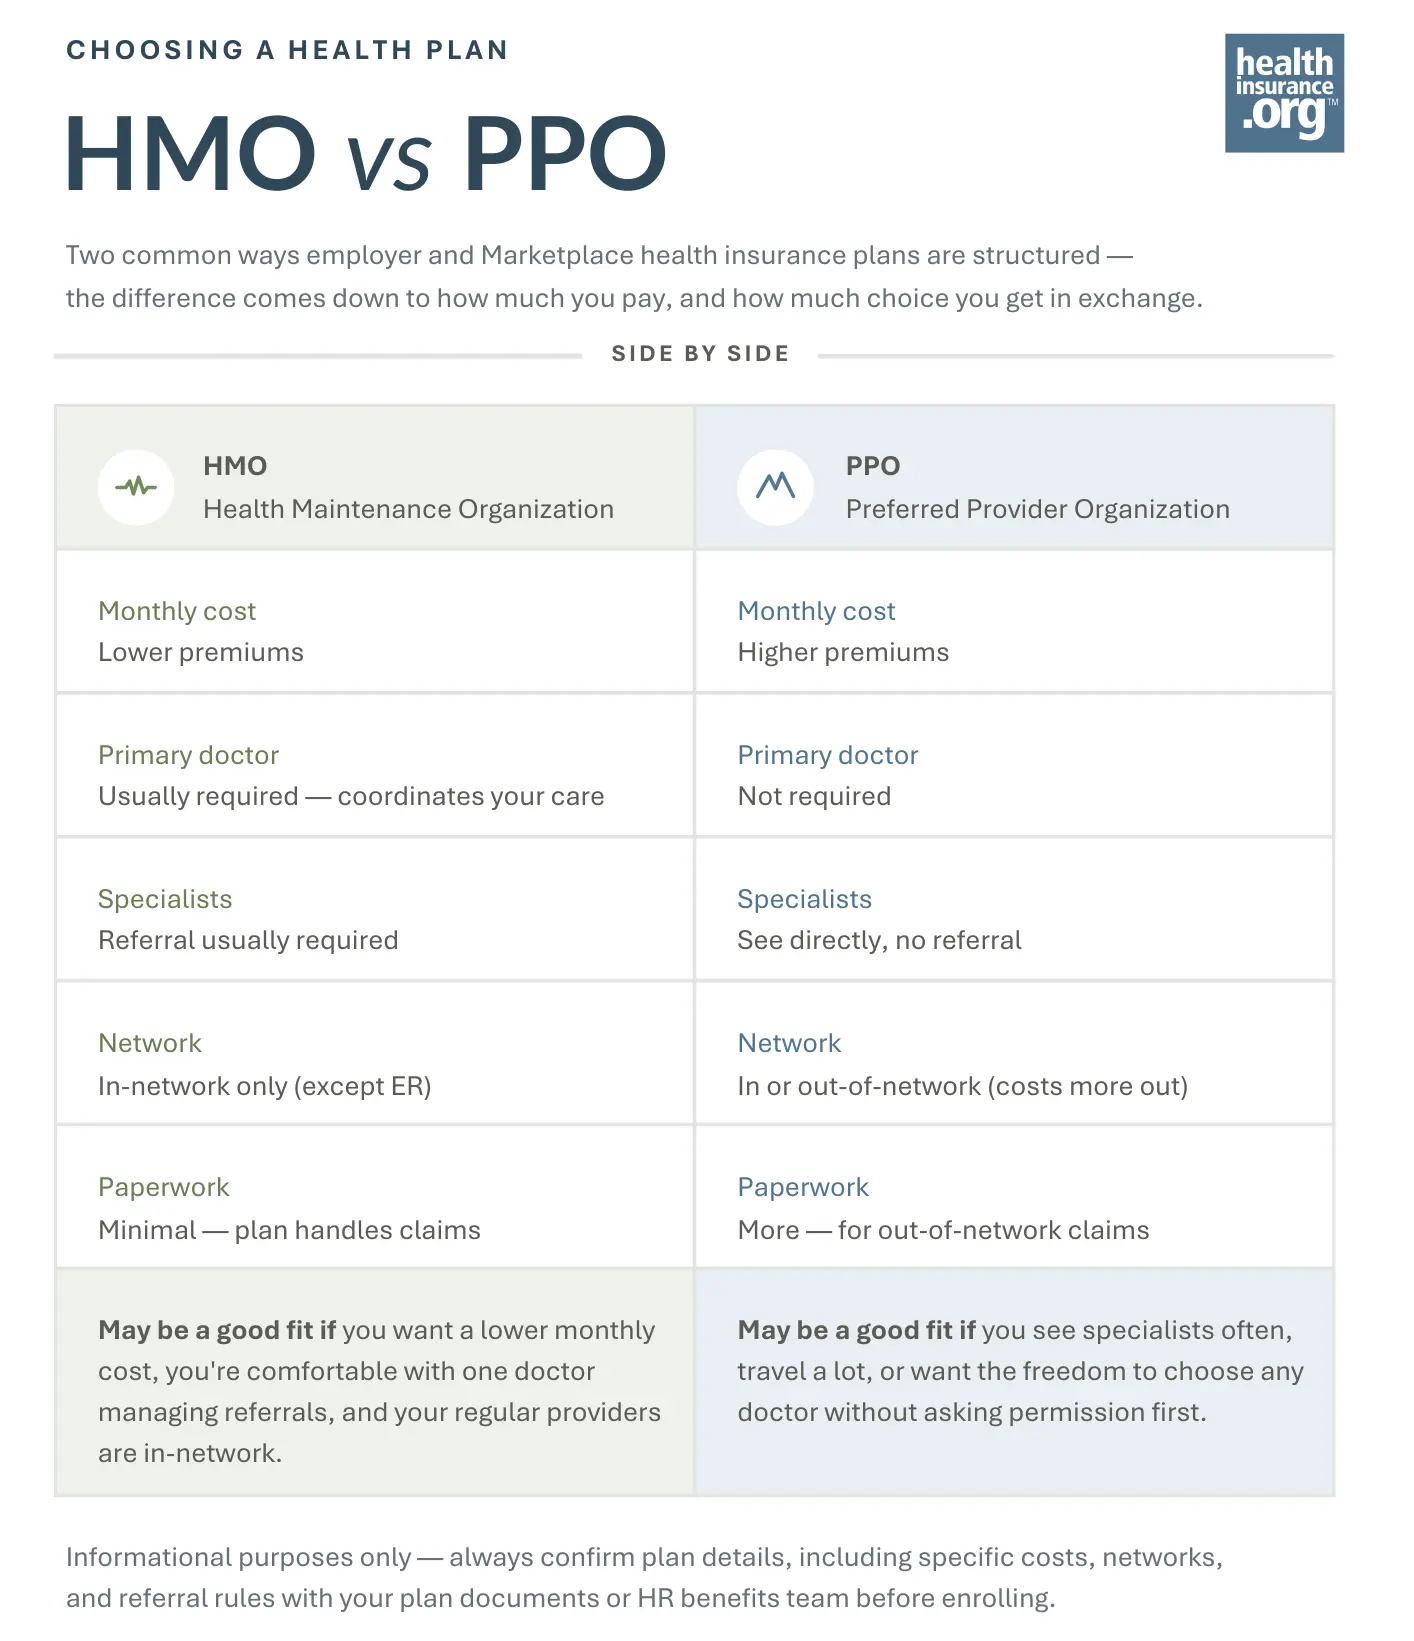
Premiums are normally lower for HMO plans, and there is typically no deductible or a low one. Some HMO plans, including those offered by Medical Mutual, do not require you to pick a PCP or have a recommendation to see a specialist. For more HMO specifics, read our About HMO Strategies short article.
They likewise feature a network of suppliers, however there are less restrictions on seeing non-network service providers. In addition, your PPO insurance will pay if you see a non-network company, although it might be at a lower rate. Here are some essential functions: You can see the medical professional or specialist you 'd like without having to see a PCP.
Nevertheless, your benefits will be much better if you stay in the PPO network. Premiums tend to be higher, and it prevails for there to be a deductible. Read a more in-depth meaning of PPO in our PPO Plans article. As pointed out above, Distinctions in between HMO (Health Care Organization) and PPO (Preferred Provider Company) plans include network size, capability to see specialists, expenses, and out-of-network protection.
Smart Wealth Security Using Modern Life Insurance
PPOs generally provide greater flexibility in seeing experts, have bigger networks than HMOs, and offer some out-of-network protection. Here are the comparison points in more information. A defining feature of HMO and PPO strategies is that they both have networks. Networks are one method to lower health care expenses network service providers consent to offer discount rates in exchange for access to a health insurance's members.
In basic, PPO networks tend to be more comprehensive, consisting of more medical professionals and health centers than HMO plans, giving you more option. Networks will vary from insurance company to insurance company, and strategy to plan, so it's best to research each plan's network before you decide. Many HMOs will need you to choose a medical care doctor, who will be the main point of contact for your healthcare.
Costs for experts will not be covered without a PCP recommendation. In contrast, PPOs tend not to require choice of a PCP, and you can normally see a professional without a recommendation, and still have these costs covered. For both PPO and HMO strategies, your expenses for care will be least expensive if you get it from in-network companies.
For HMOs, out-of-network services are typically not covered at all, other than for emergency situations. PPOs differ from HMOs because PPO plans will typically provide some coverage for these kinds of services, but protection for in-network providers will be much better. The extra coverage and flexibility you obtain from a PPO suggests that PPO strategies will normally cost more than HMO plans.
Medicare Fraud Prevention ChecklistFinding Affordable Individual Medical Quotes for 2026
This is the amount of health care costs you should pay before your plan begins to cover your expenses. Not all HMOs have deductibles, however when they do, they tend to be lower than PPO deductibles.
49% of covered workers had PPO plans in the survey, while HMOs covered 16%. When it concerns your own health strategy option, it may sound like a cliche, but when selecting between an HMO or PPO strategy, it is not necessarily about which is better, but which is best for you.
If your financial scenario dictates that cost is most important, you might seriously consider going with an HMO strategy. Typically speaking, costs for HMO plans will be less.
Medicare Fraud Prevention ChecklistUnlike the majority of HMO health insurance, you will not likely require to pick a medical care physician, and you won't generally need a recommendation from that physician to see a specialist. A PPO network will likely be larger, providing you a greater selection of in-network medical professionals, specialists, and facilities to pick from.
Finding Cheap Individual Health Quotes for 2026
With HMOs, out-of-network protection will usually be limited to emergencies; non-emergency services are not normally covered at all. To assist you weigh the pros and cons laid out above, here's a fast summary of them: With any strategy, inspect the company network to see if your preferred providers remain in the plan's network, given that staying in-network will save you cash.
You might discover that the specific HMO plan you're considering includes your favored providers, or at least enough of them to satisfy your needs.

Latest Posts
Essential Part D Enrollment Tips in 2026
Comparing Individual Health Insurance Quotes Online
Strategies for Financial Security Using Life Insurance